Systems built for Florida — scoped for insurability.
Roof, HVAC, electrical, plumbing, windows, solar. In South Florida these aren't maintenance items — they're what carriers and lenders look at first. We identify condition issues and document possible mitigation features; the carrier determines eligibility, credits, and premium.
Enjoyability
Marketability
Insurance
FL extreme weather
The 6 disciplines
Each scoped one way: insurability + weather
 The insurability gatekeeper
Roofing
Quiet confidence through hurricane season
Explore roofing The 10-month system
Mechanical (HVAC)
Explore mechanical (hvac) The silent dealbreaker
Electrical
Explore electrical Behind-the-wall risk
Plumbing
Explore plumbing Credits you can see through
Windows
Explore windows Honest sunshine math
Solar
Explore solar
Built for Florida's extremes.
Roofs, systems, and envelopes delivered under a separate written agreement by the appropriately licensed Academia construction entity, to keep South Florida homes insurable through heat, wind, humidity, and rain.
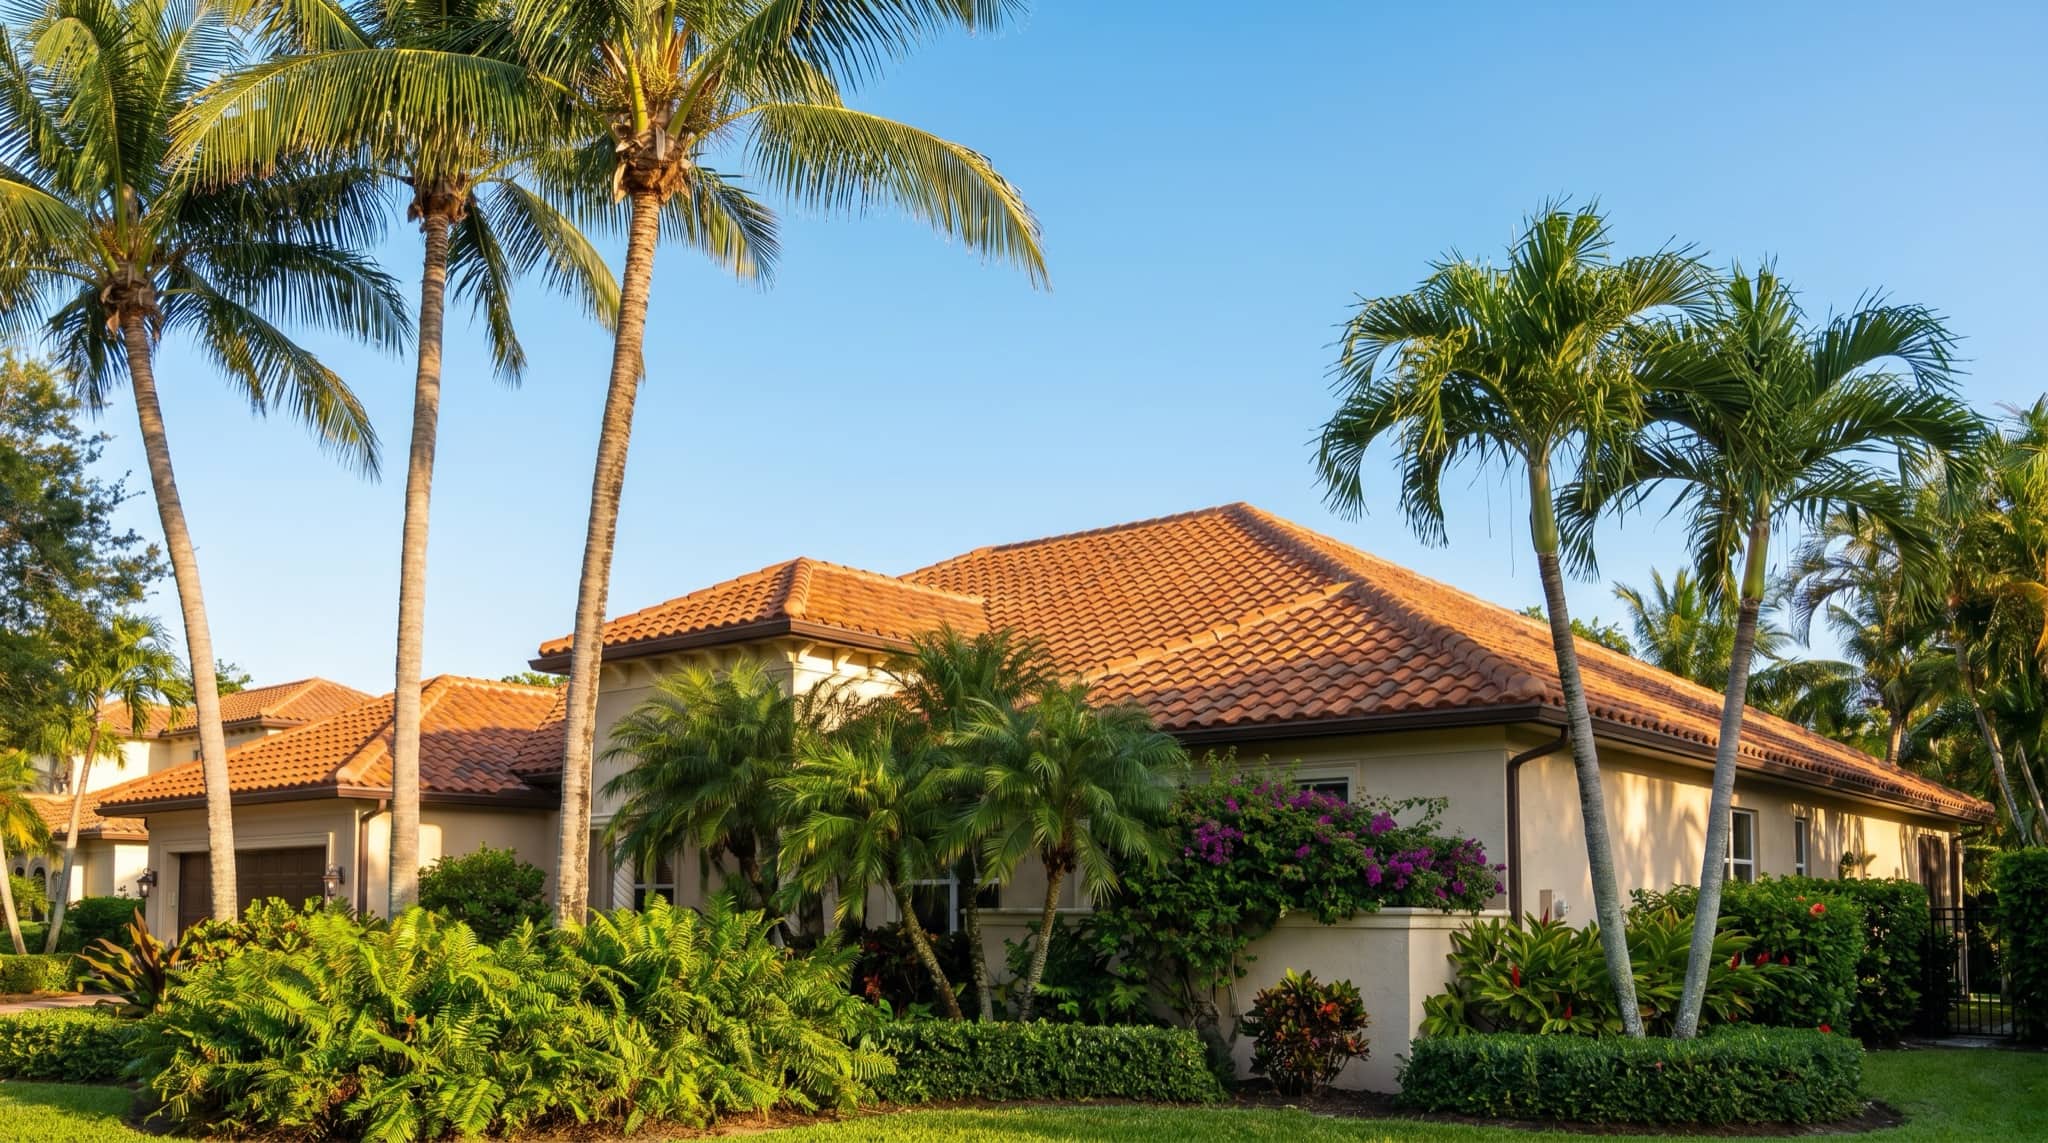
Barrel-tile roof on a Miami home against a blue sky, South Florida. 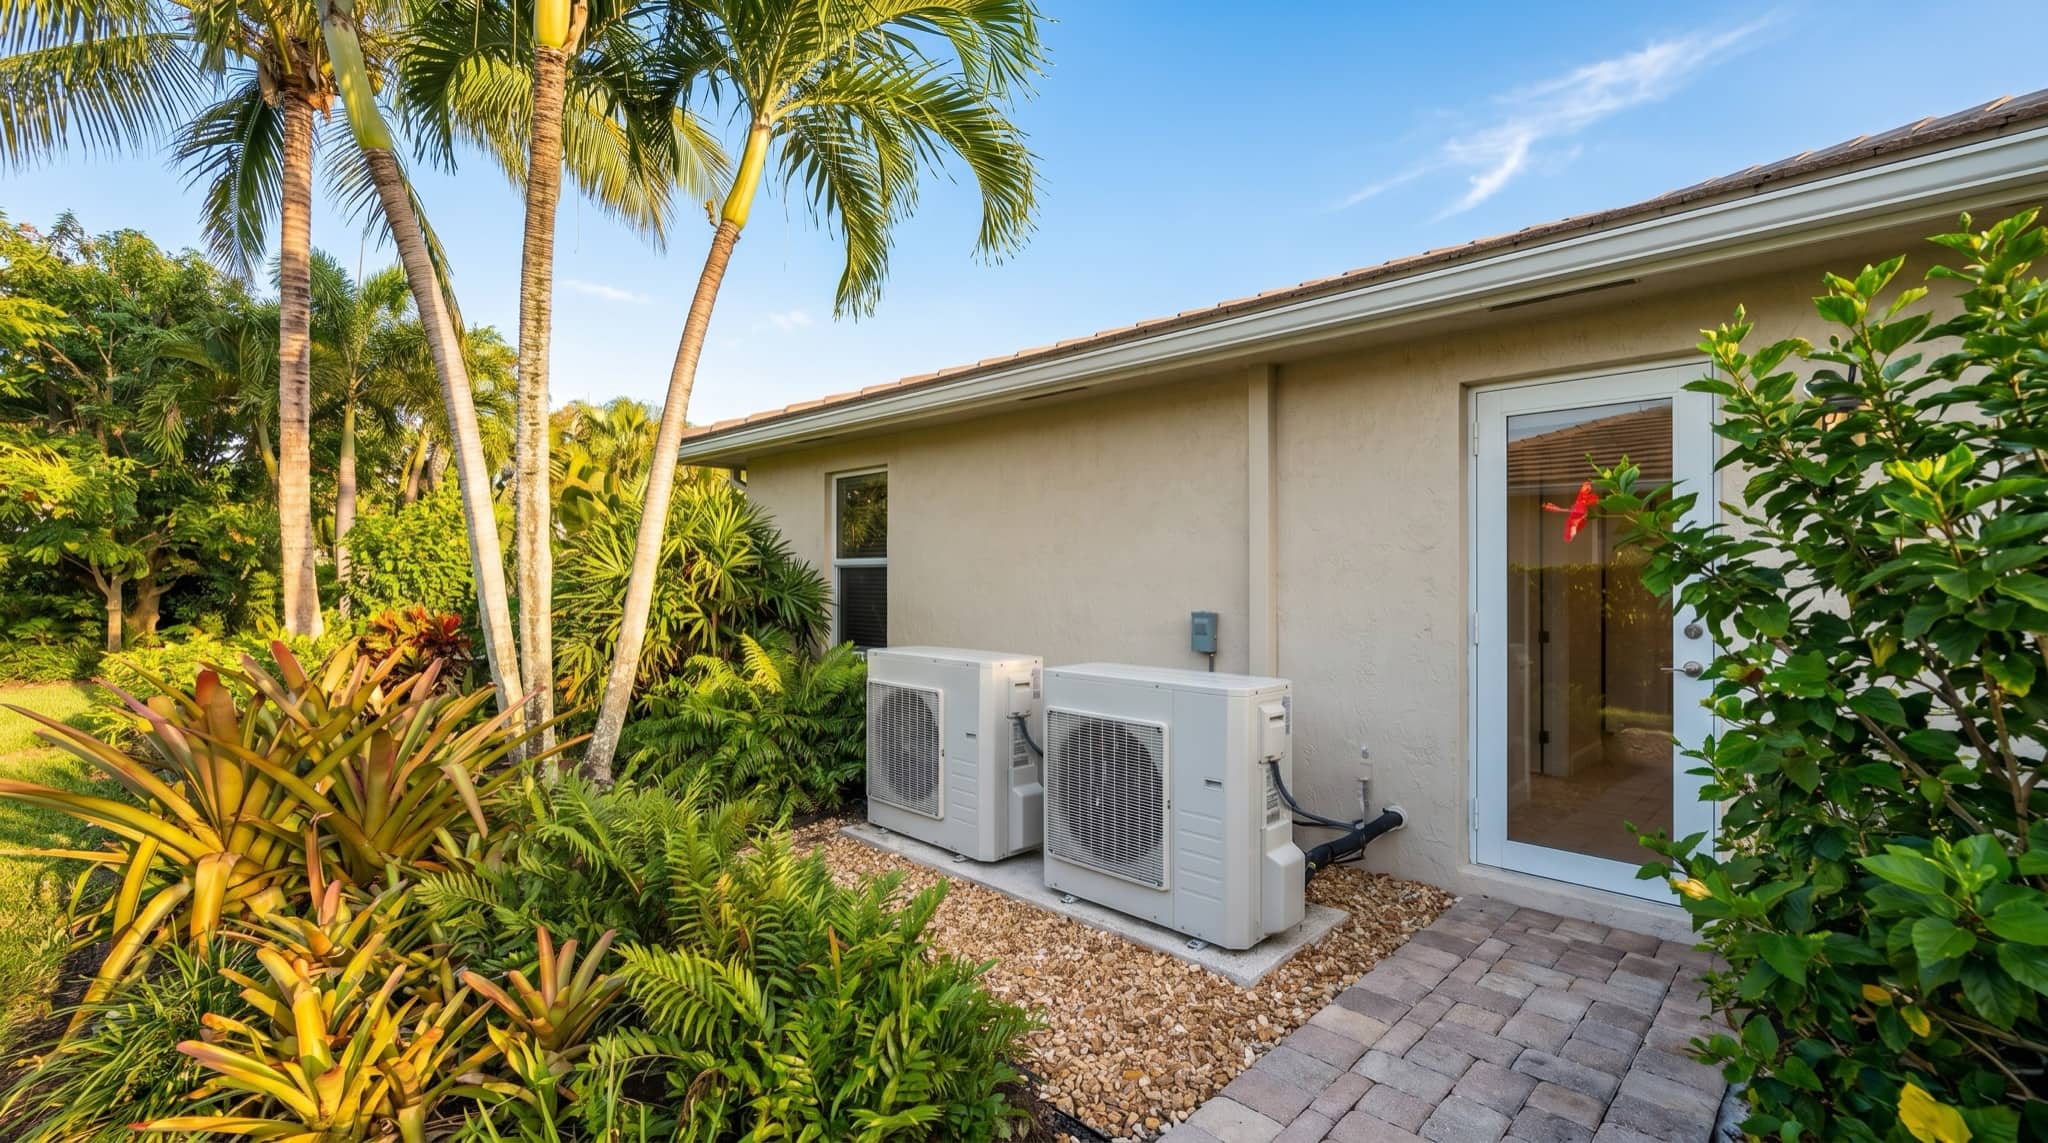
Outdoor AC condenser units beside a Florida home with palms, South Florida. 
Impact-resistant windows on a modern Florida home exterior, South Florida.
Get a home performance estimate
A licensed Academia team reviews every request — usually same day.
Home Improvement
The spine over there: value + speed of sale.
Systems built for Florida — scoped for insurability. — common questions
What is home performance, and how is it different from renovation?
Renovation changes how a home looks and lives. Performance work is the systems that decide whether it is insurable, financeable and comfortable — roof, mechanical, electrical, plumbing, windows and solar. In Florida those systems, not finishes, are what most often stop a sale.
Why do these systems matter so much in South Florida specifically?
Heat, wind, humidity and rain are the four forces that drive premiums here, and carriers price them directly. Roof age and construction, opening protection and electrical condition are the items an insurer asks about before it quotes.
Can a home be unsellable because of its systems?
It can be effectively unsellable to a financed buyer. If insurance cannot be bound, the loan cannot close — so a roof at the end of its life or a panel a carrier declines becomes a transaction problem regardless of how the home shows.
Should I fix systems before listing or credit the buyer?
A credit lets the buyer price the work at their number rather than yours, and the listing still photographs and inspects as-is. Fixing first is usually the stronger position, though the comparison is worth running before deciding.
Who is licensed for this work?
The real-estate brokerage holds the broker license; the roofing, air-conditioning, electrical, plumbing, solar and general-contractor licenses are held by a separate, appropriately licensed Academia construction entity, which performs the work under its own written agreement. That coordination is why a performance question can be answered with a scope and a price rather than only a referral.
What is a wind mitigation inspection?
A documentation instrument, not a structural inspection. It records hurricane-resistance features on Florida's uniform verification form. We identify the condition issues and document the mitigation features present on your home; the carrier determines eligibility, credits, and premium — confirm the specifics with your insurer.